Mastercard launches Global Money Platform for stablecoin payments, with BVNK integration and first partners Nuvei and Marqeta
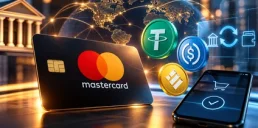
Mastercard has introduced Global Money Platform, a single payments layer for traditional currencies and stablecoins, with its first large-scale integration through BVNK, which Mastercard acquired in August 2026. For PSPs, banks, and high-risk merchants, the point is straightforward: Mastercard is now trying to make stablecoin flows behave like ordinary payments infrastructure, with one API instead of a patchwork of separate rails.
- Global Money Platform lets companies hold fiat and stablecoins, convert between them in real time, and send cross-border transfers. Mastercard says all of this is available through one API that can be embedded into banking or payment services, which is the part operators will care about if they want stablecoin support without building the plumbing from scratch.
- The platform also supports card payments directly from stablecoin balances, plus transfers of digital assets with settlement to recipients’ bank accounts in local currency. In practice, that means Mastercard is packaging stablecoin functionality into familiar payment outcomes: card spend, bank payout, and cross-border movement.
- Mastercard says it uses Mastercard Move, its global transfer network, which covers more than 17 billion payment destinations. The company also says that by 2027, transfer capabilities will cover more than 40 currencies in more than 200 countries and territories, with card issuing available in more than 130 countries.
- Among the first partners on Global Money Platform are Nuvei and Marqeta, with Ontop, Bolt Group, and Almond FinTech also joining the integration. That lets them offer stablecoin operations under their own brands, which is the usual business model here: the infrastructure vendor does the heavy lifting, and the partner sells the end product.
- The platform is already available through BVNK. Mastercard says the broader strategy is to connect traditional payment infrastructure with digital assets for cross-border settlement, liquidity management, and payouts, while also increasing competition with Visa, which is developing its own stablecoin tools.
For high-risk operators, the operational question is not whether stablecoins exist; it is whether a card network can turn them into something banks, fintechs, and merchants will actually wire into production. Mastercard is clearly betting that the answer is yes, provided the regulatory requirements, transaction costs, and business appetite line up.
Related news
All news →
Weekly high-risk digest
Regulation, sanctions and payment news across your verticals — once a week, free.
Please check your inbox and click the link to confirm your subscription.
Please enter a valid email address!